Credit Card Churning 101
I booked an Air Canada Business Class seat from Montreal to London and paid just $80 in taxes and fees. The same seat in cash was $5,895. The $5,815 in between came from credit card churning.
The bank won't explain this game to you, so let me. This post is the 101: how the game works, how to protect your credit score, and which cards to open first. But first, the question you're already asking: where does a $5,815 seat come from?
Why churn at all
Because the money is already moving. Every month you spend it on groceries, gas, coffee, going out, and the Netflix, Amazon Prime and Spotify subscriptions you keep meaning to cancel. About half of my monthly spending goes on a credit card. You can even pay rent by credit card now (a post on that is coming). You're spending the money either way. The only question is what your card gives back, and played well, that's a lot more than you'd think.
A standard credit card gives you about 1% back on all of that. That's the floor I set for myself: if a card can't do 1%, it doesn't live in my wallet. But do the math on the floor. 1% of $1,000 a month is $10, so $120 a year. I just showed you a $5,815 seat from the same spending. Everything between those two numbers is what a few years of reading fine print taught me, and it is what proper credit card churning is: with a smarter strategy, the same spending can return 5%, even 10%, and on a good day a lot more.
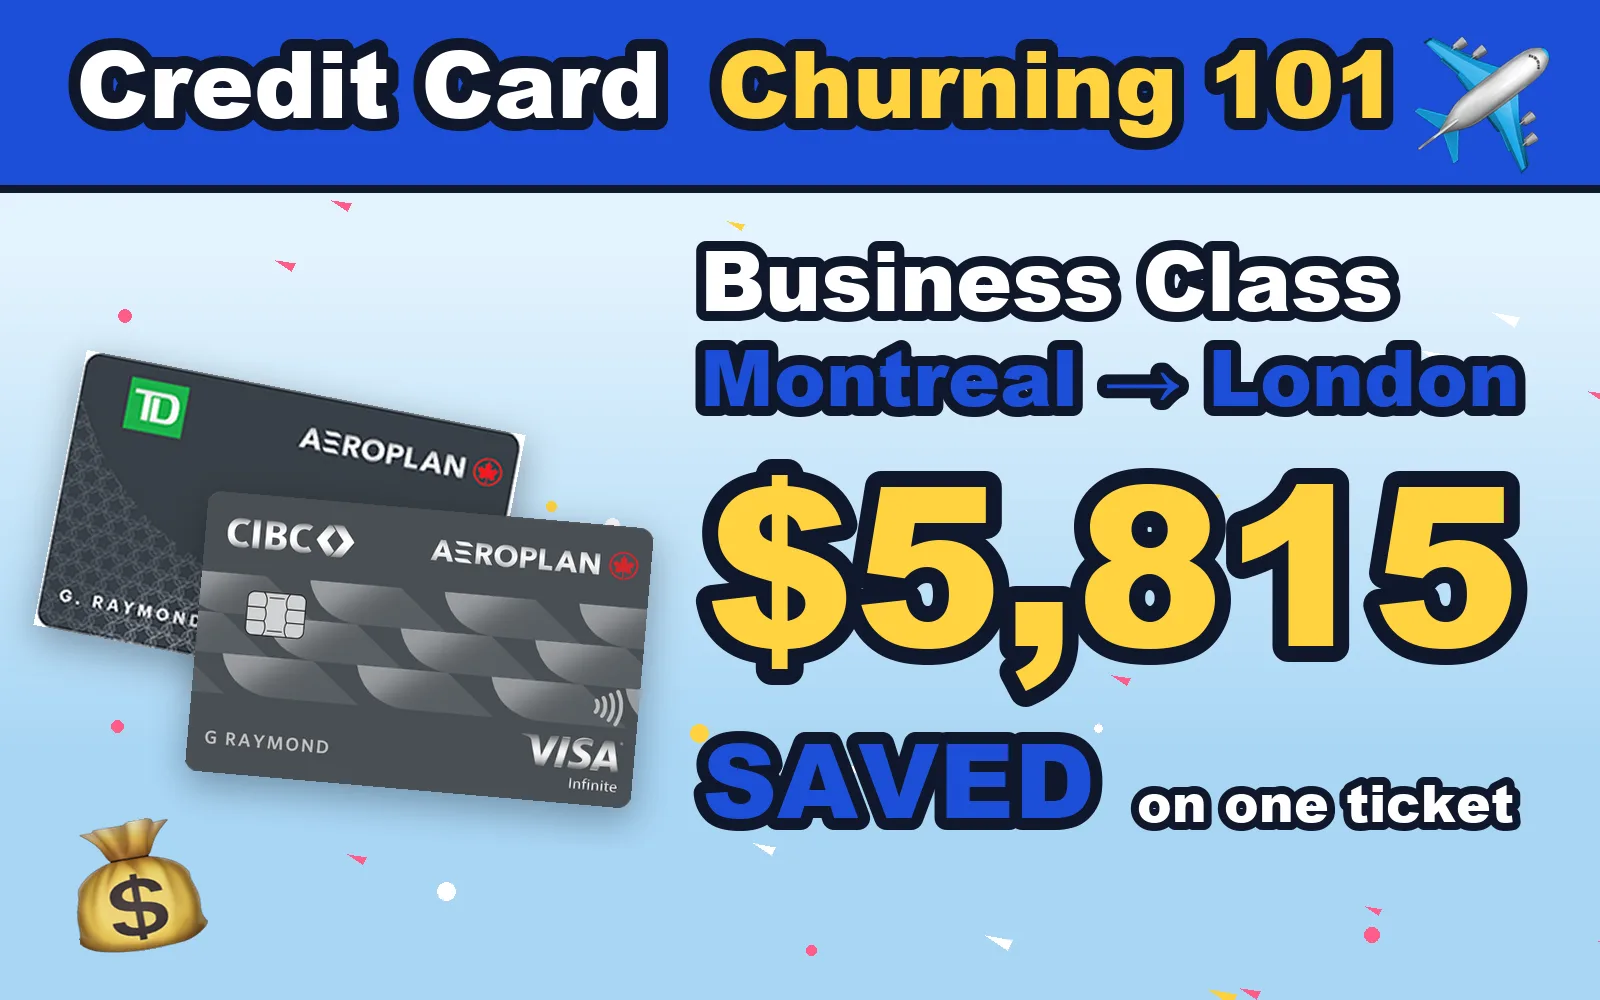
The whole post in one picture. The numbers are real and the receipts are below.
What the top end looks like
Let me show you the best case before the theory, because it is the reason this hobby exists.
The TD Aeroplan Visa Infinite is currently offering up to 50,000 Aeroplan points, with the first-year fee waived. To unlock all of it you put about $12,000 through the card over the year. That spending earns points too, roughly another 15,000 at the card's regular rates. Call it 65,000 points in the account, from money you were going to spend anyway.
On the day I wrote this, Air Canada wanted 65,600 points plus $80.41 in taxes for a one-way business-class seat from Montreal to London on October 17, so I booked it. The same lie-flat seat, same route, same day, paid in cash, was $5,895.
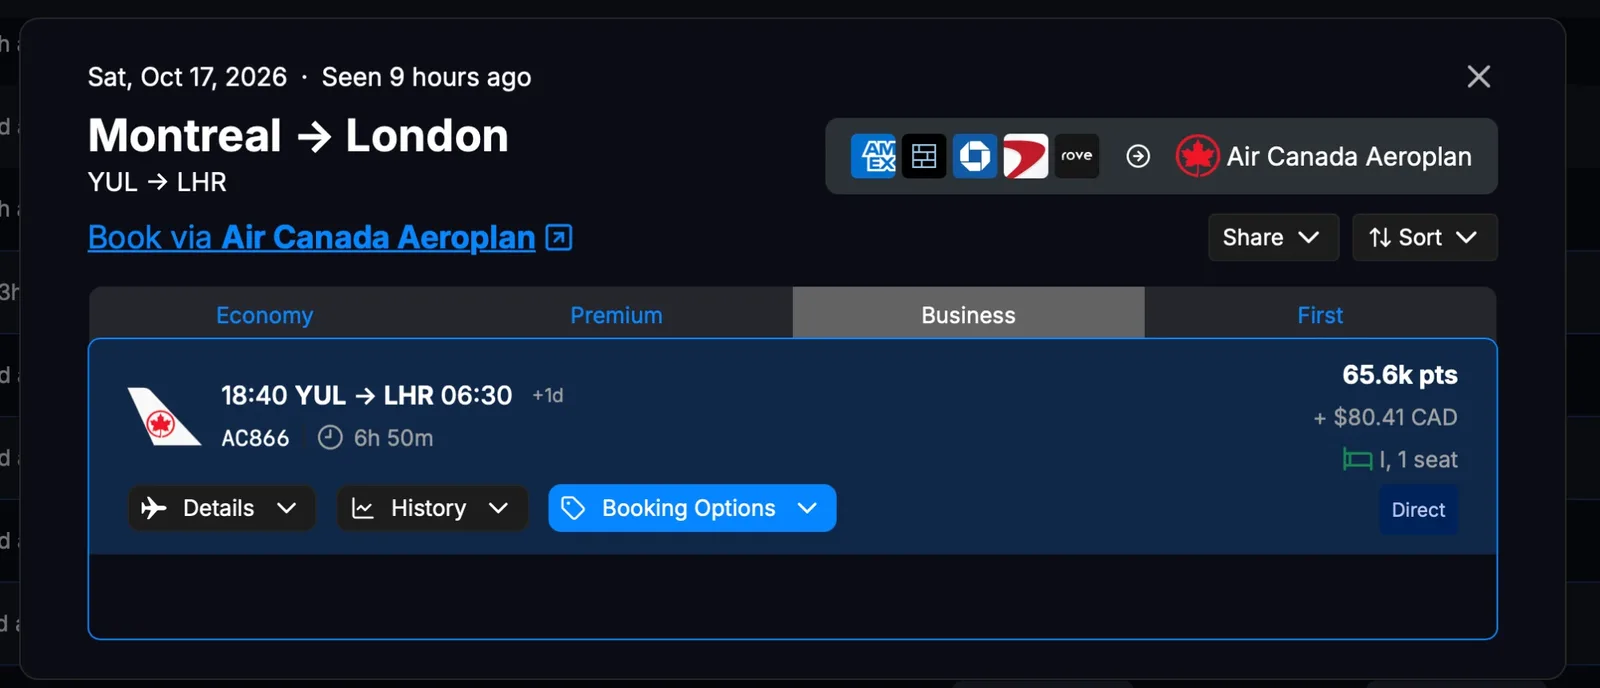
Award search for the Aeroplan booking, September 6, 2026. 65,600 points plus $80.41 in taxes for a lie-flat seat, one seat left. I took it.
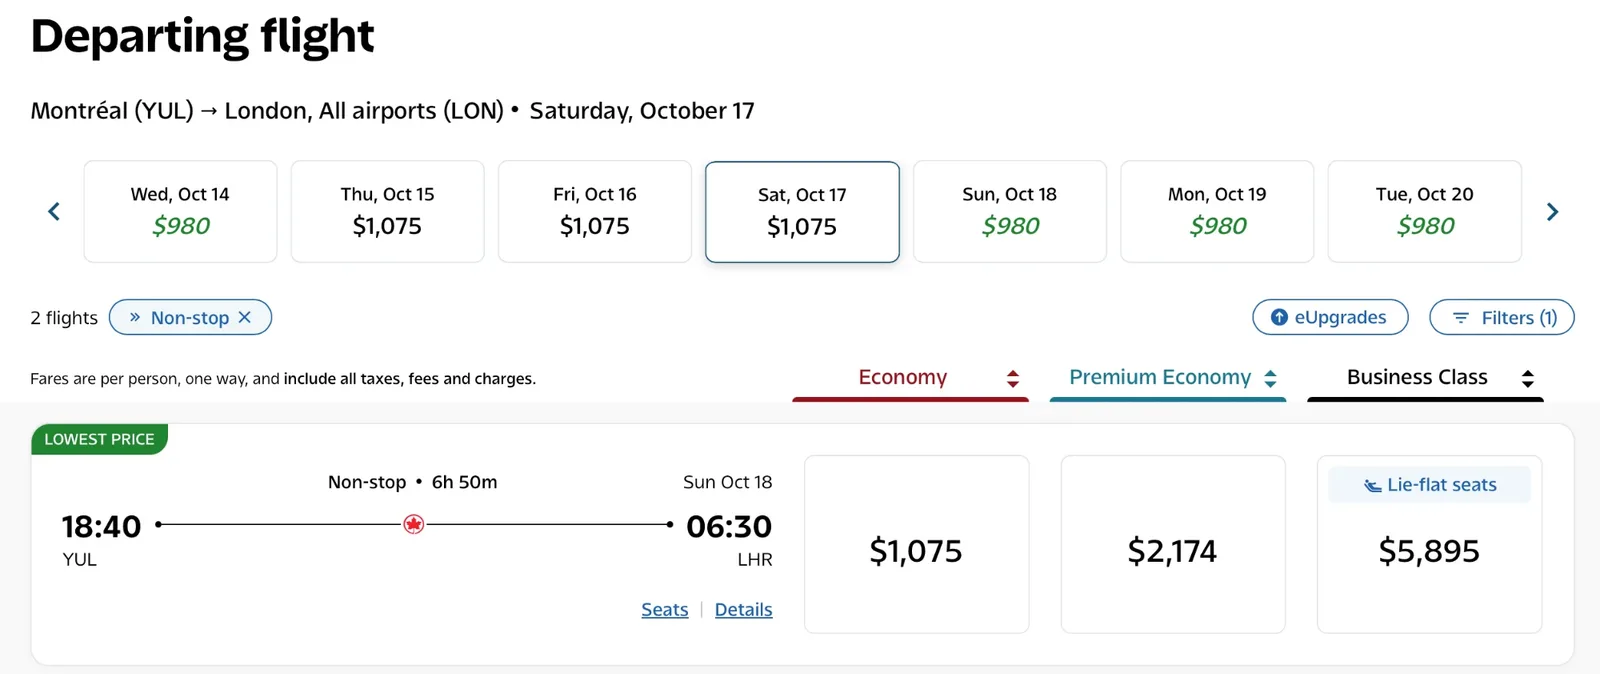
aircanada.com, Montreal to London for October 17, 2026, the same flight as the award above. Fares are one way, per person, taxes included. The right-hand column is the one that matters: $5,895.
So here is the math. $12,000 of everyday spending. $80 out of pocket. A $5,895 seat, which means $5,815 saved on one ticket. A plain 1% cash-back card would have paid me $120 on that same $12,000.
Two honest caveats, because that is the whole point of this site. First, this is the ceiling, not the average. Business class is where Aeroplan points are worth the most, close to 9 cents each on this booking versus the 2 cents I use for planning everywhere else in this post. Second, it only counts as $5,800 if you would actually fly business class. If you would have bought the $1,075 economy seat, the honest value of those points is closer to $1,000. Still eight times what the 1% card pays, but a long way from $5,815.
So what is credit card churning?
Banks and financial institutions throw huge welcome bonuses at new customers. Why? Because they want to make money from you (a lot more on that in an upcoming post about how banks actually profit from credit cards). The bonus is the bait.
Take the BMO CashBack Mastercard. Right now it's offering 5% cash back for your first 3 months. Sounds great. We have better offers than this (more on that below), but it's a clean example of how the game works.
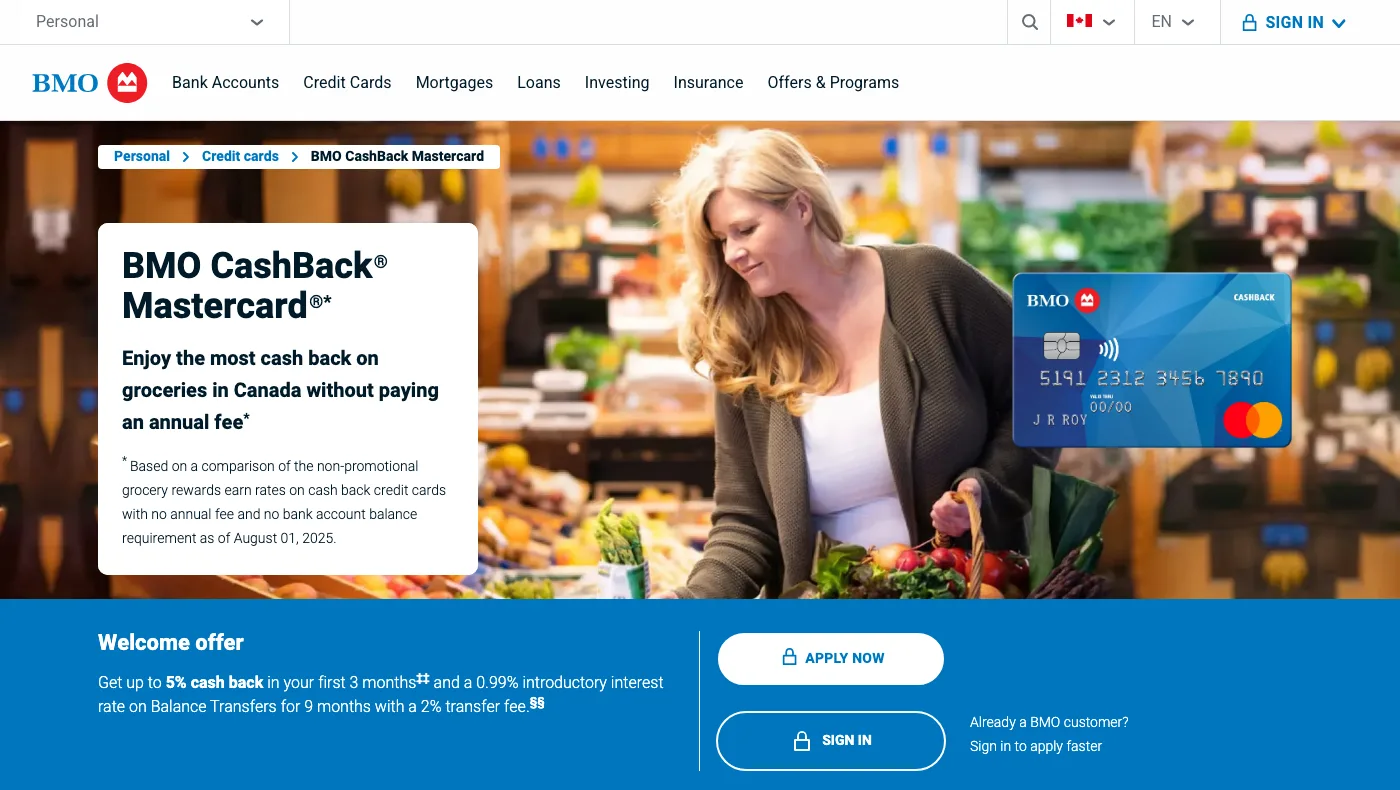
Screenshot from bmo.com, September 6, 2026. Look at that "5%" and then look at the tiny ‡‡ next to it. That symbol is where the real story lives.
Churning is simple in concept: open a card for the welcome bonus, collect it, then move on to the next one. Obviously we don't want to do all that work for three months of slightly better rewards. We want to be strategic and a little lazy: put in as little time as possible, but still walk away with a meaningful pile of cash or points. That's exactly what this post is about.
Churning 101: know what you want, do the math, ignore the slogan
Before you apply for anything, answer three questions:
- What do you actually want? Cash in your account? Aeroplan points for a business-class seat? Something you can spend anywhere? Pick one. A "10% back" card is useless if the 10% is on something you never buy.
- What's the real return? Not the headline. The dollars you pocket, after the annual fee, after the caps, on the spending you'd do anyway.
- How much effort do you want to put in? Some people love juggling five cards. Some want one card and zero thinking. Both are fine, but be honest about which one you are.
And please, don't get fooled by the marketing slogan. "5%" or "10%" sounds like a lot. In reality, those rates almost always apply only to your first few hundred dollars of spending. Here's what that ‡‡ footnote on the BMO page actually says, in plain English:
- The 5% applies to your first $2,500 of spending: $500 on groceries, $500 on recurring bills, and $1,500 on everything else.
- Maxed out, that's $125. Total. That's the ceiling.
- Against a 1% baseline, you would have earned $25 on that $2,500 anyway. So the offer is really worth about $100 extra, roughly a 4% bump on a small slice of spending.
I'd rate that a third-tier welcome offer. Not bad for a no-fee card, but nowhere near the good stuff. For comparison, the Aeroplan card I'll mention below hands you about $1,000 in flights in year one, with the annual fee waived. Same amount of paperwork, ten times the payoff. That's why we do the math.
Things to be aware of before you start
1. Opening a new card dings your credit score in the short term. Every application is a hard inquiry, and your average account age drops. So don't open five cards at once. Space them out (I like roughly 90 days apart). On top of that, almost every welcome offer comes with a minimum spend you have to hit within a window (usually 3 months). If you open two cards at the same time, you have to spread your spending across both and still clear both hurdles. That's how people end up buying junk to chase a bonus, and that's how the bank wins. I'll write up how I hit minimum spends without spending a dollar extra in a separate post.
2. Annual fees are the enemy. First-year waivers are your friend. A lot of the best cards charge $120 to $150 a year but waive it for the first year. The play is to take the bonus in the fee-free year, then, right before the year-two fee posts, either downgrade to the no-fee version of the card or cancel it. In practice this means you'll be rotating your card lineup once or twice a year. More on when a fee is actually worth paying in a later post.
3. Always pay your card in full, on time. I can't say this enough. Banks make their credit card money from people who don't pay in full. Those people are literally subsidizing your fat rewards. Credit card interest runs 20 to 25%, which makes it the worst loan you will ever take. Carry a balance for one month and you've wiped out the entire bonus. If you're not confident you can pay in full every month, churning is not for you yet. Fix that first. (I'll break down the bank's whole revenue model in a separate post.)
4. Will churning wreck your credit score? Short answer: no. But that "no" rests on two conditions. First, you pay on time, every time (see point 3). Second, you keep your credit utilization low. If you have $10,000 in total limits across all your cards, try to keep your balances under 30% of that, so under $3,000 at any statement. Here's the fun part: opening a new card actually helps here, because more total limit means a lower utilization rate for the same spending. Short-term dip from the inquiry, long-term boost from the extra room. The one exception: don't open new cards in the year before you apply for a mortgage.
The cards I'd look at first
This post is already getting long, so I'll save the full "here's exactly which cards I churn and in what order" for a follow-up. But if you want to start now, these are the three I'd point you at:
| Welcome offer (as of Sept 7, 2026) | Annual fee | Who it's for | |
|---|---|---|---|
| CIBC Aeroplan Visa Infinite | Up to 50,000 Aeroplan points (≈ $1,000 in flights) | $139, waived year one | Anyone who flies |
| TD Aeroplan Visa Infinite | Up to 50,000 Aeroplan points | $139, waived year one | Same, if you'd rather bank with TD |
| TD Cash Back Visa Infinite | $350 cash (10% on your first $3,500 of groceries, gas and bills, first 3 months) | $139, rebated year one | Cash, not points |
| Scotia Momentum Visa Infinite+ | $300 cash (15% on your first $2,000, first 3 months) | $120, waived year one | Cash, if you're new to Scotiabank |
1. Aeroplan: the CIBC Aeroplan Visa Infinite or the TD Aeroplan Visa Infinite. If you fly at all, and especially if a business-class seat is on your wish list, this is the best welcome offer in the country for the effort involved. Both cards are free for the first year and both are currently dangling up to 50,000 Aeroplan points, which is roughly $1,000 in flights if you redeem them properly. Both earn 1.5x on groceries and gas, so the everyday earn is respectable too. I'd churn the CIBC one first, then come back for TD. A full breakdown of every Aeroplan card in Canada is next on my list.
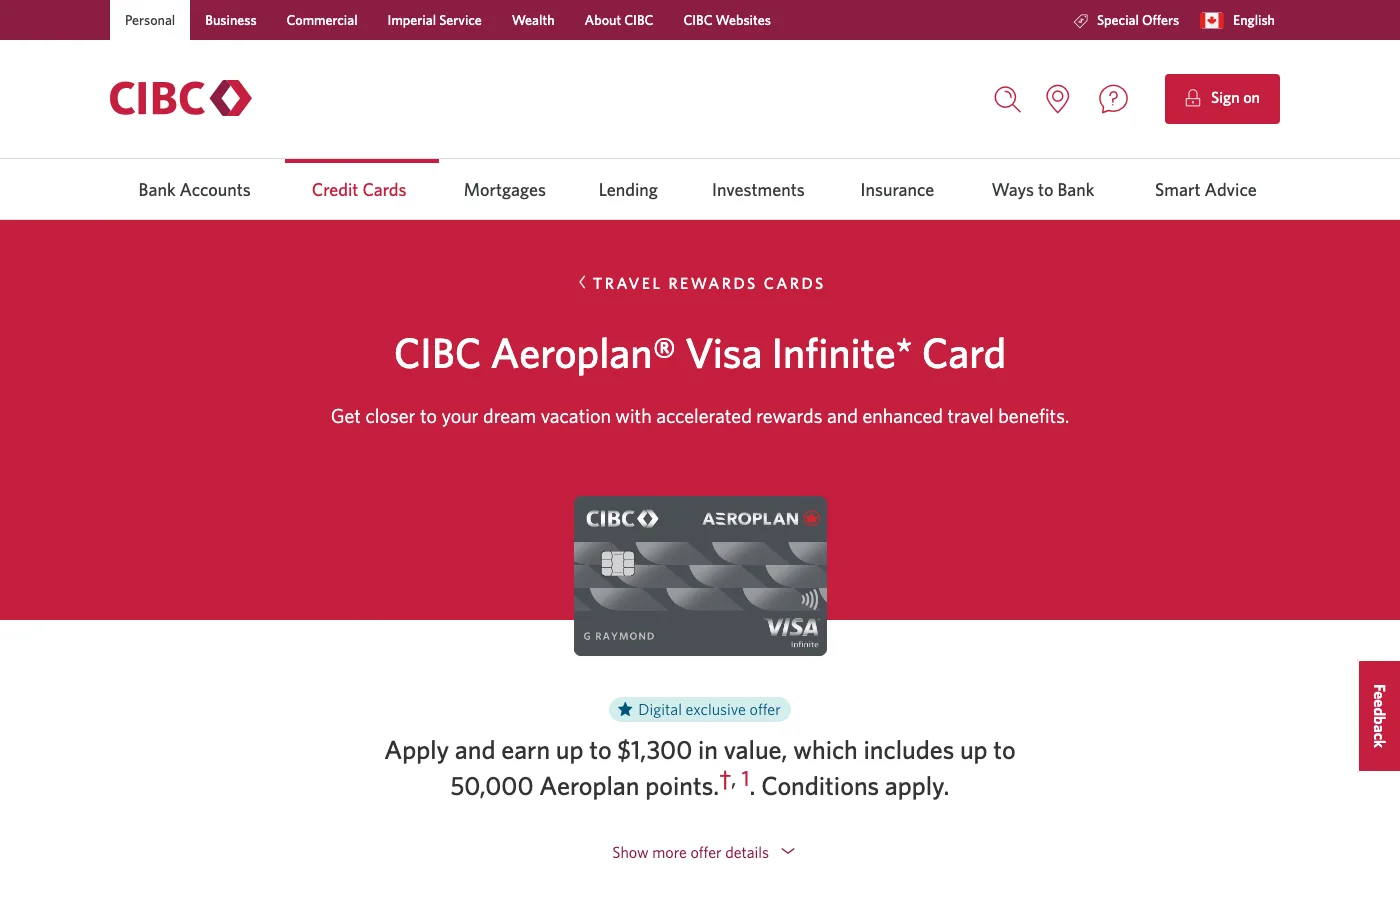
cibc.com, September 6, 2026. "Up to $1,300 in value" is the bank's number. Mine is about $1,000, because I only count the points and only at what they buy on a flight.
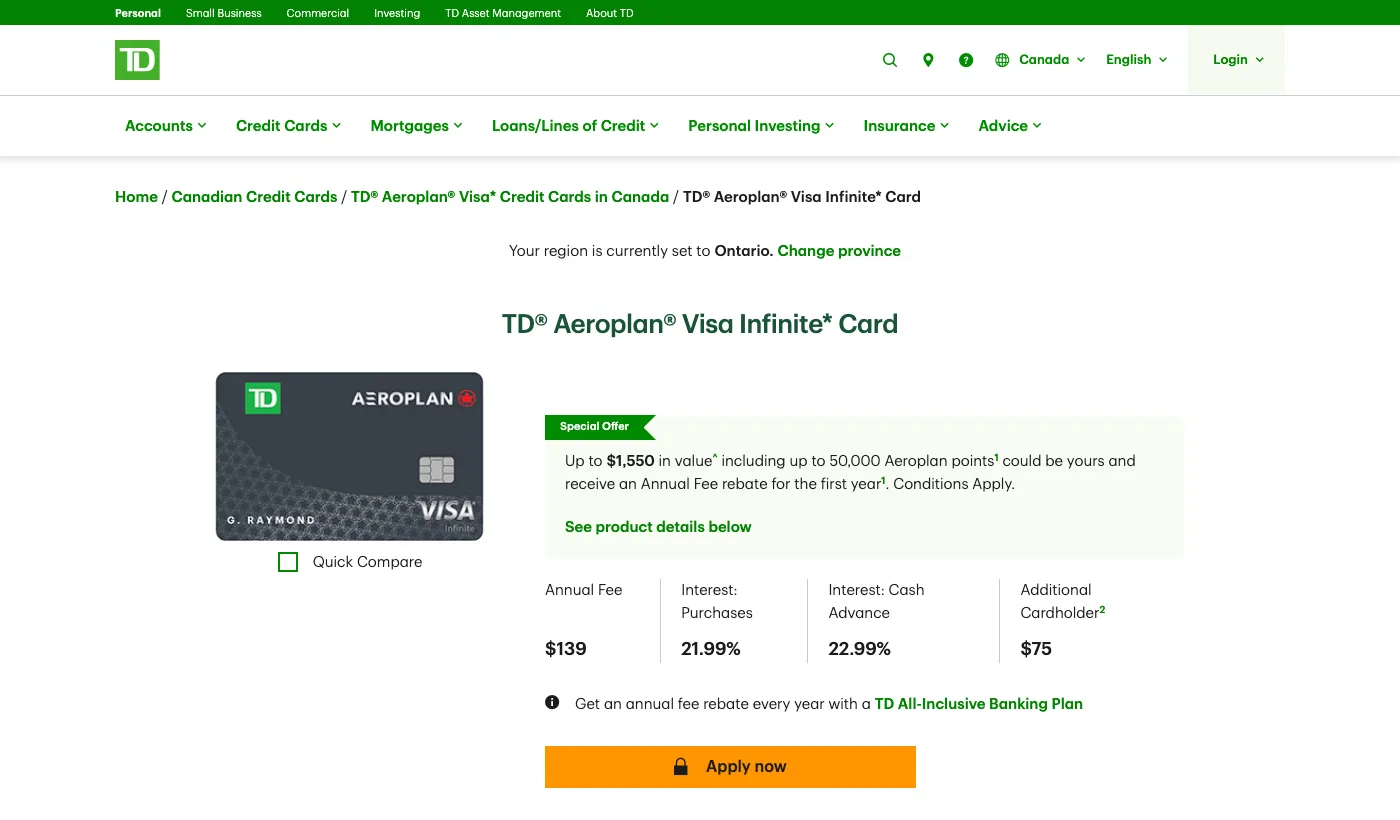
td.com, September 6, 2026. Notice the $139 fee, 21.99% interest and $75 for an extra cardholder right under the offer. That's the honest part of the page.
2. Cash back: the TD Cash Back Visa Infinite. If you'd rather have money than points, this pays the most right now: 10% cash back on your first $3,500 of groceries, gas, transit and recurring bills in the first 3 months, which is $350 in cash. The first-year fee is rebated, so the card costs you nothing in year one. TD's page says "up to $600 in total value". The other $250 is the fee rebate and a free roadside-assistance membership. A rebated fee is not a reward, it is the absence of a cost, so I don't count it, and you shouldn't either. That trick is everywhere in this hobby. After the bonus the card earns 3% in those same categories, which makes it one of the few churn cards worth keeping if you spend enough. If not, downgrade to the no-fee TD Cash Back Visa before the year-two fee posts and keep the account open.
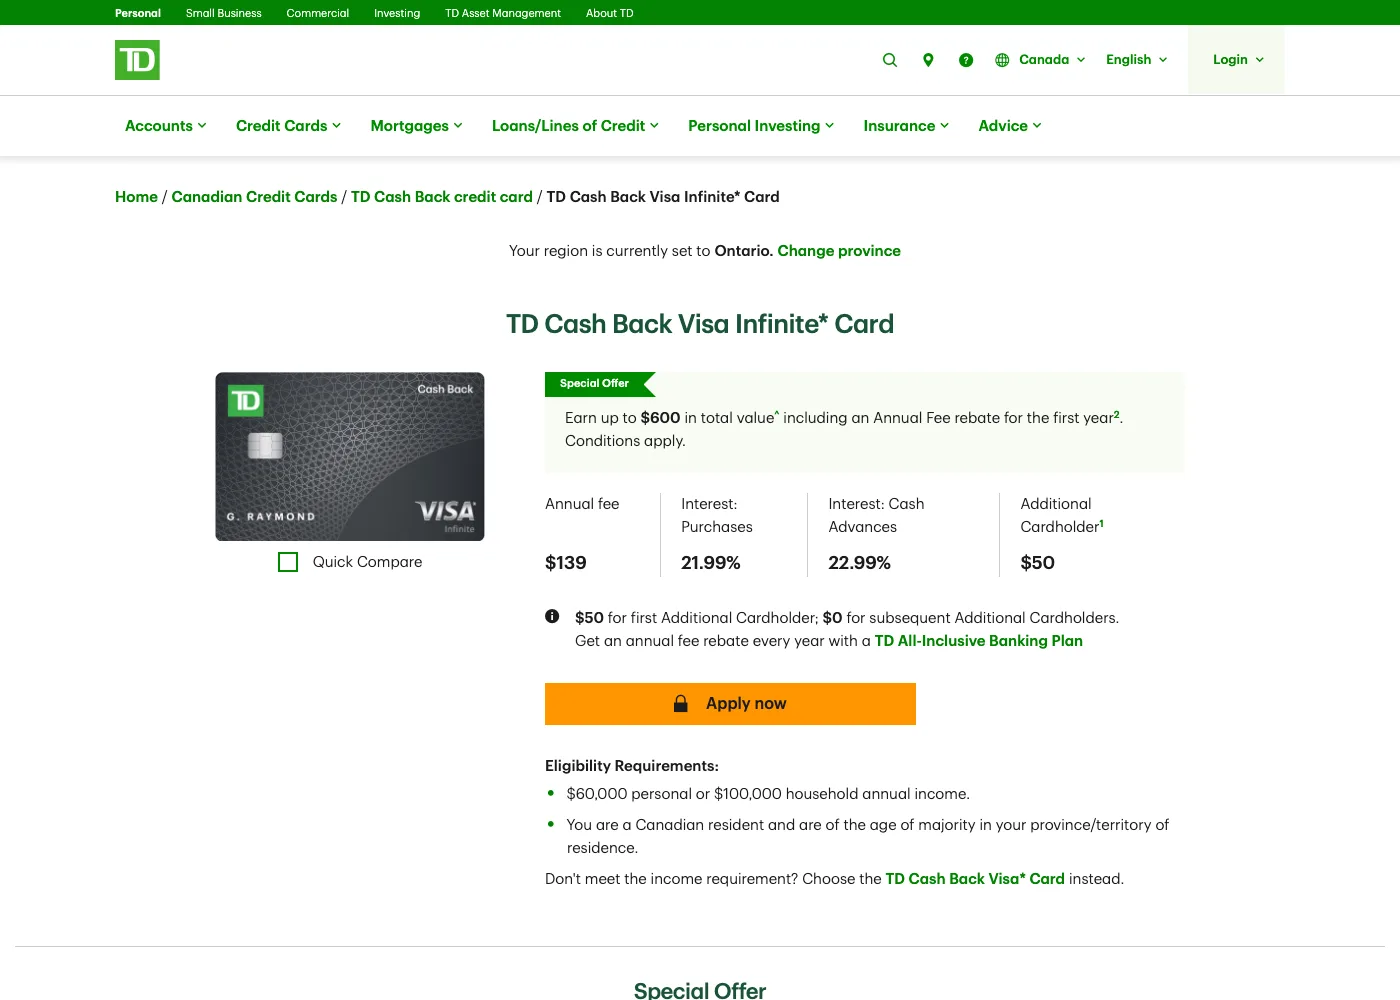
td.com, September 7, 2026. "Up to $600 in total value." The cash is $350. The rest is the fee rebate and a roadside-assistance membership. Look at the $139 fee and 21.99% interest right underneath.
3. More cash back: the Scotia Momentum Visa Infinite+. 15% cash back on everything for your first 3 months, up to $2,000 in purchases, so $300 in cash, and no fee in year one. Simpler than TD's version, because every purchase counts. Three catches: the offer ends November 1, 2026; you're not eligible if you've held any Scotiabank personal credit card in the past two years; and the bonus shows up about five months after you open the account, so don't panic when it isn't there in month four. The regular rate is 4% on groceries and recurring payments, the best in the country, so this is another card you might keep. The runner-up in cash back is the CIBC Dividend Visa Infinite: 10% on your first $2,000 ($200) plus $50 for setting up a pre-authorized payment, so $250 in cash, fee rebated. CIBC advertises it as "up to $350 in value". Same trick, same answer. The full cash-back comparison is coming soon.
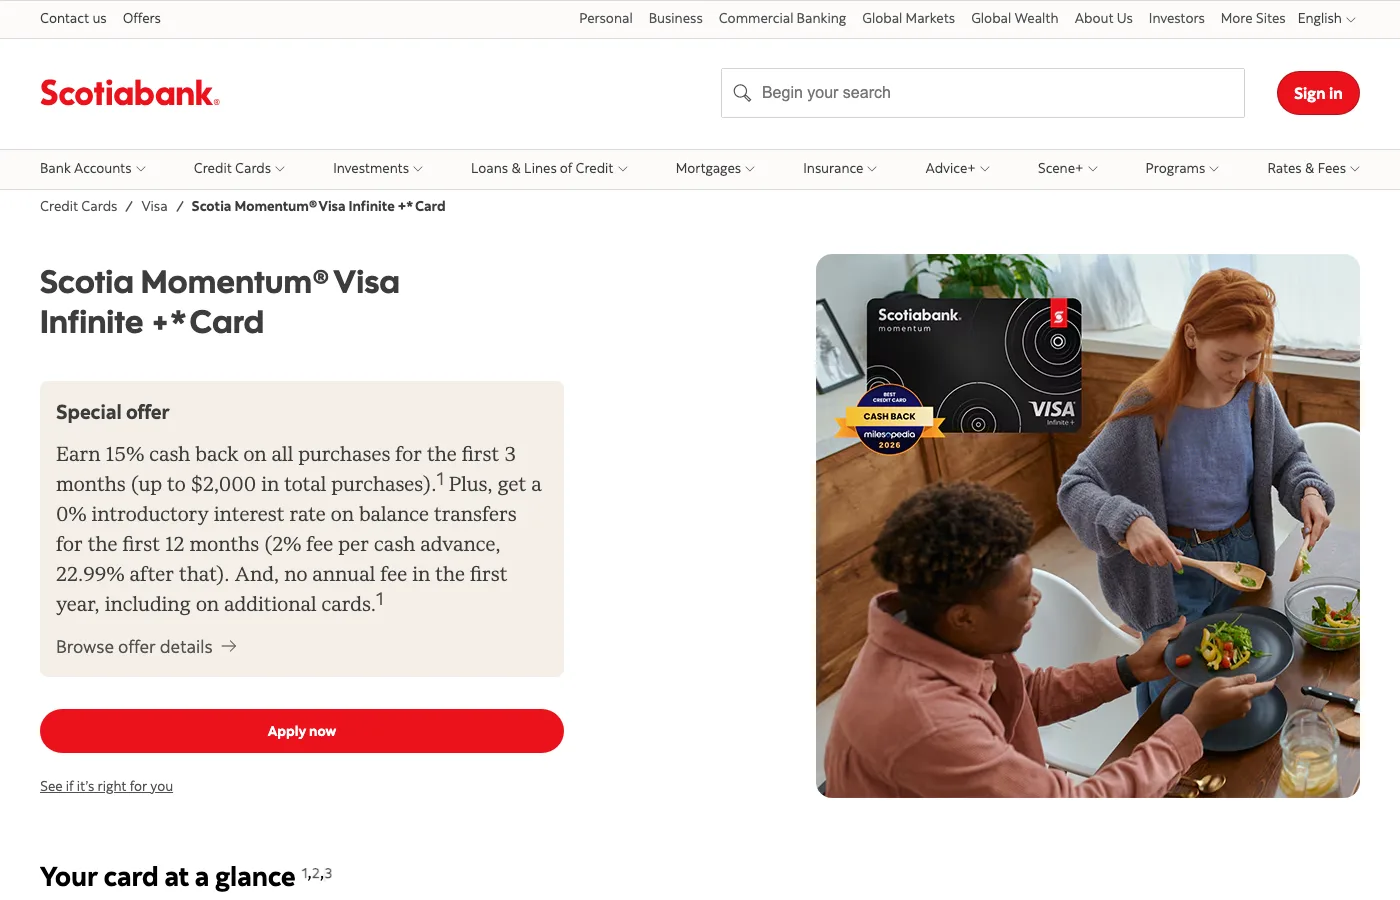
scotiabank.com, September 7, 2026. 15% on the first $2,000 is $300. The 0% balance-transfer line underneath is aimed at people carrying debt, which is not what this post is about.
A word on Amex. Amex welcome bonuses are once per lifetime per card, so you get one shot at each, and you want to spend it on a big one. The Gold Rewards Card, which a lot of guides recommend, pays 60,000 Membership Rewards points for putting $1,000 a month on it for a year, about $1,200 in flights, but its $250 fee is not waived, so you net roughly $950 for $12,000 of spending. The TD and CIBC Aeroplan cards above pay more for the same spending, for free. Save your Amex shot for an elevated offer like the one the Aeroplan Reserve is running right now, 70,000 points for $7,500 in 3 months, and even then remember the $599 fee. That is a card for later in your churning career, not the first one you open. Amex also isn't accepted at Costco or most Loblaw-banner grocery stores, which matters when the bonus depends on your grocery bill.
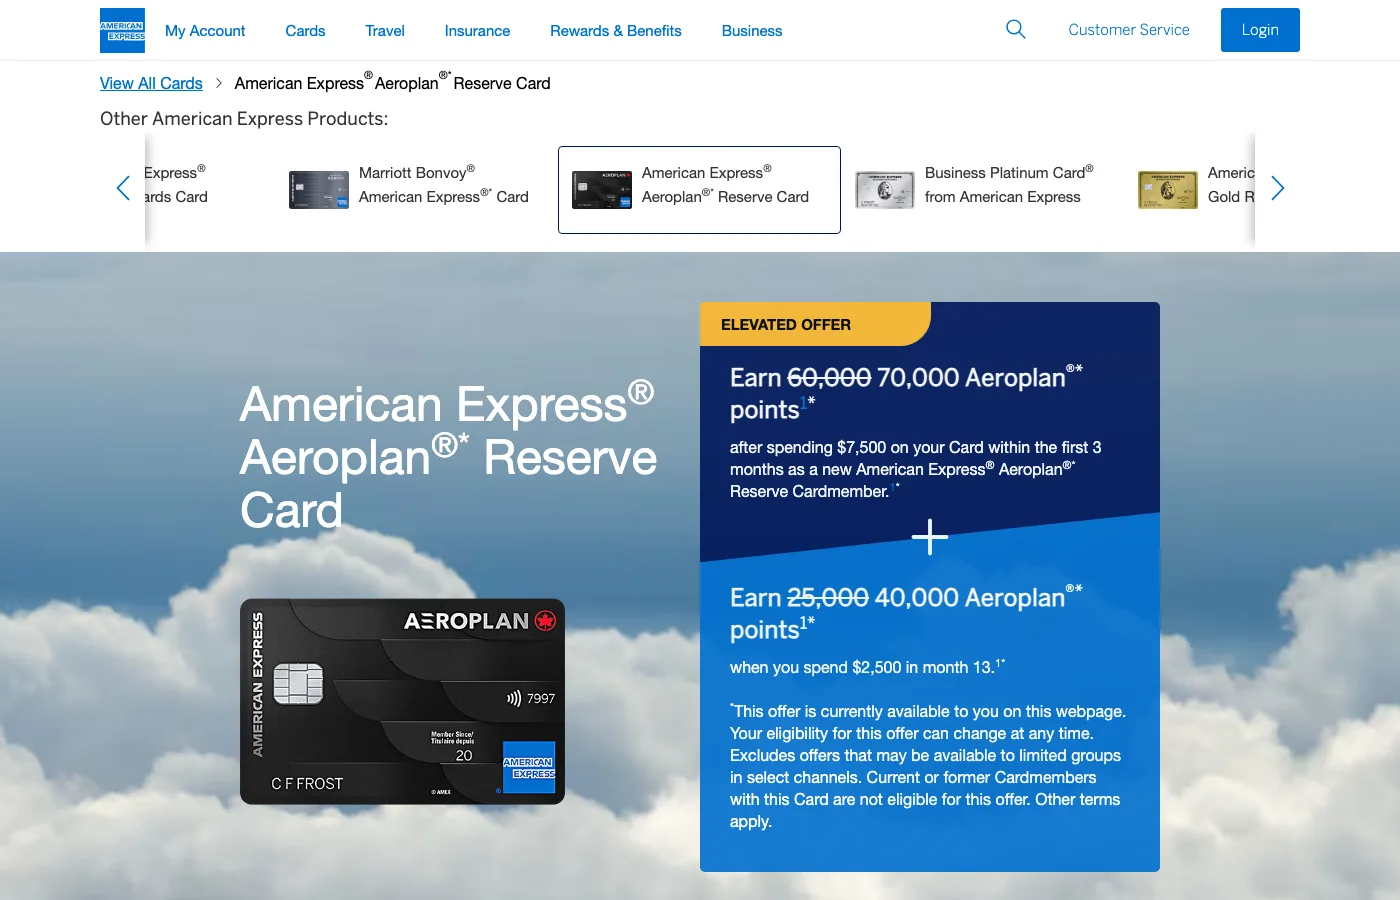
americanexpress.com, September 7, 2026. 70,000 points after $7,500 in three months, then 40,000 more for spending $2,500 in month 13, which means paying the $599 fee twice. "Current or former Cardmembers with this Card are not eligible" is the once-per-lifetime rule in writing.
Want the exact math?
If you want to see the actual returns on these cards, every dollar of spend, every fee, every cap, that's the next post. After that: which cards I churn and in what order, how I compare rewards programs in the first place, and how the banks make money off all of this. This is post one. Stick around.
Now go pay off your balance. Then we can talk. 💳
Before you apply: confirm the live offer on the bank's own page. Everything in this post is dated September 6 and 7, 2026, the days it was written and checked, and banks change their offers whenever they like. General information, not financial advice, and no affiliate links. Full details in our Terms of Use.