TD First Class Travel Visa Infinite
Spend $1,250 a month for six months on the TD First Class Travel Visa Infinite and you end up with about 180,000 TD points, worth $900 in travel. The fee is rebated in year one. Here is how.
This is my first Card of the Month, and I picked it because I'm applying for it myself. Below: what TD points are actually worth, what $900 buys (I priced a weekend at the Château Frontenac), how Expedia For TD works, what the lounge visits are good for, what it takes to get the bonus, and when I'll cancel or downgrade before the fee comes back.
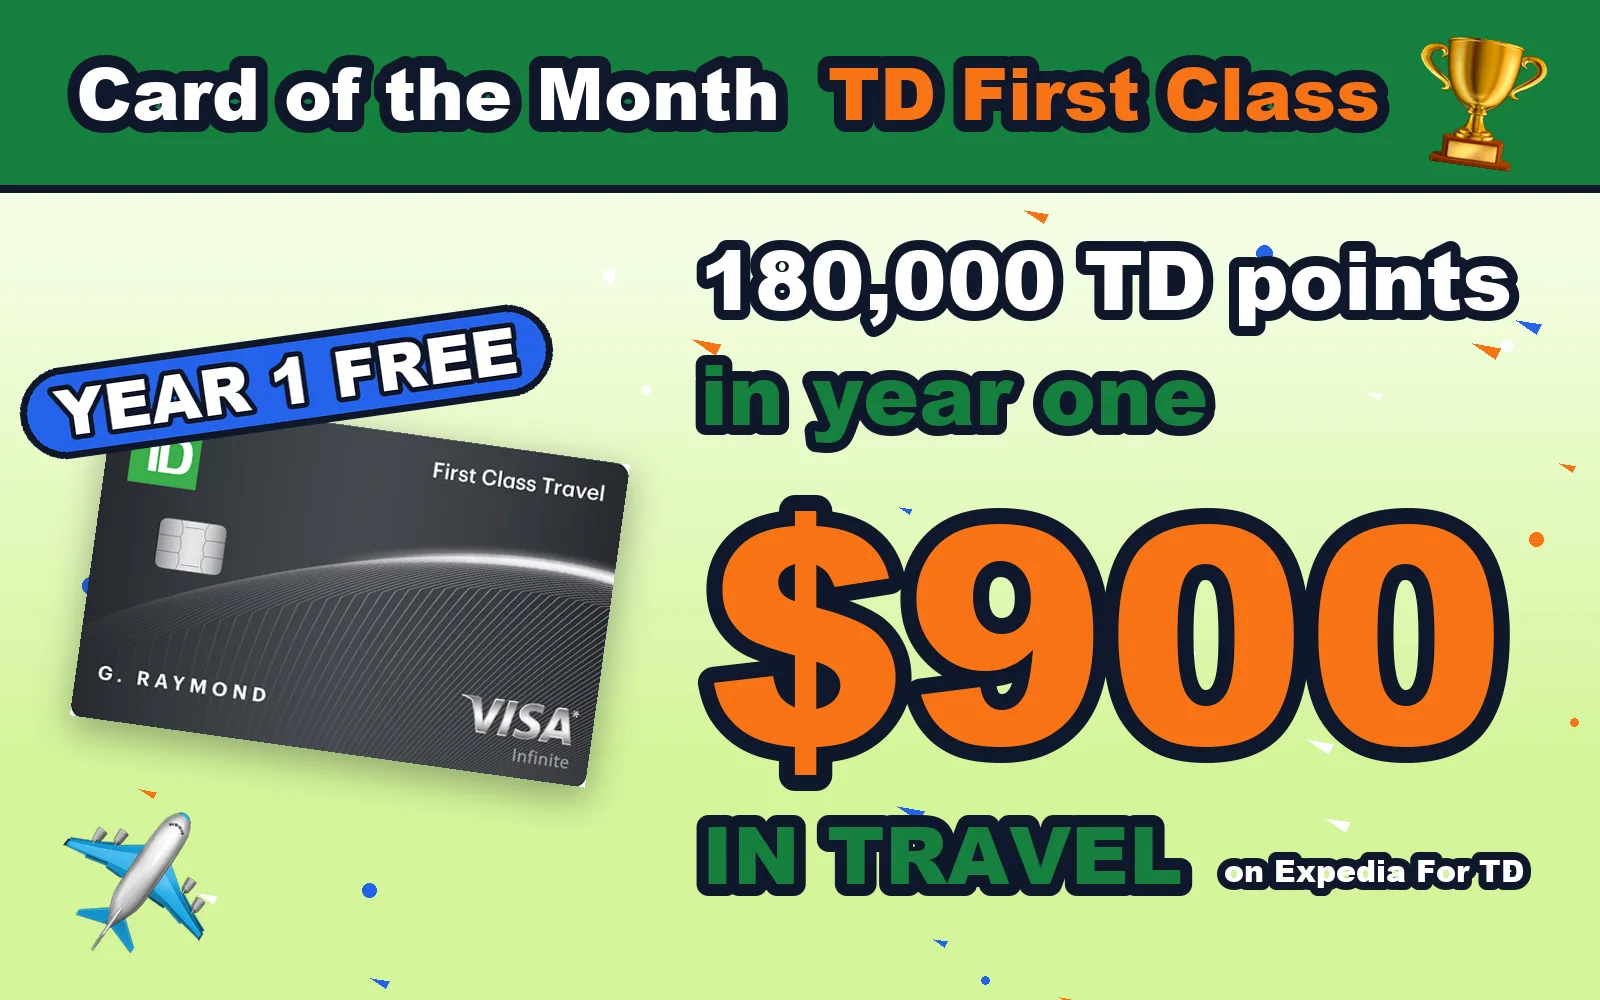
The whole post in one picture. The numbers are real and the receipts are below.
Why this card, why now
The TD First Class Travel Visa Infinite is offering up to 160,000 TD Rewards Points. It is a huge number. The problem is that nobody knows what a TD point is worth. 160,000 sounds like a free trip to Japan. It isn't.
And 160,000 is only the welcome bonus. The $7,500 you spend to get it earns points too. So this post does one thing first: it turns the whole pile into dollars. Then it shows you how to actually spend them, and how I plan to get in and out without paying a fee.
What 160,000 TD points are worth
TD points have one good use and several bad ones.
| How you use the points | TD's rate | 160,000 points |
|---|---|---|
| Travel booked on Expedia For TD | 200 points = $1 | $800 |
| Anything else (travel booked elsewhere, statement credit, gift cards) | as little as 400 points = $1 | $400 |
The $800 is TD's own number. Its footnote says the 20,000 first-purchase points are worth $100 and the 140,000 spend bonus $700, "travel value at Expedia For TD". The $400 comes from TD's rewards terms, which only promise "a minimum value of 400 TD Rewards Points per $1" for every other way of redeeming. Same points, half the money. So the rule for this card is simple: redeem on Expedia For TD, or don't bother.
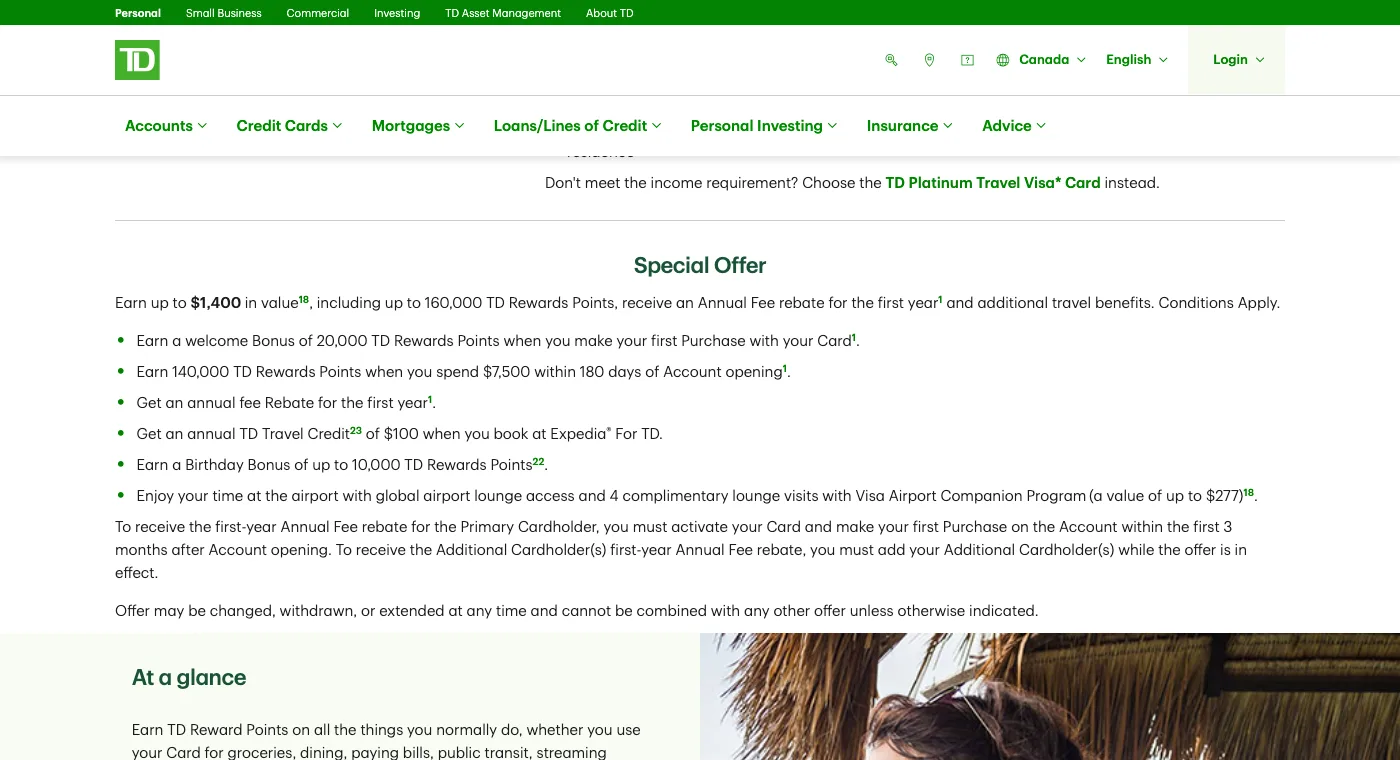
td.com, October 24, 2026. The headline says "up to $1,400 in value". The second bullet is the one that matters: $7,500 within 180 days.
What about TD's "$1,400 in value"? It is $800 of points plus a $189 fee rebate, the $100 travel credit, a $50 birthday bonus and $277 of lounge visits. A rebated fee is not a reward, it is the absence of a cost. The travel credit only pays if you book a hotel (more below). The lounge value assumes you would have bought a lounge membership. The bonus alone is $800, plus whatever you'd really use from the rest.
The bonus is only part of it
To get the 140,000 you spend $7,500, and that spending earns its own points: 6 per dollar on groceries, dining and public transit, 2 per dollar on almost everything else. So your real total depends on where the $7,500 goes.
| How you spend the $7,500 | Points from the spending | Total with the bonus | On Expedia For TD |
|---|---|---|---|
| All on "everything else" (2 per $1) | 15,000 | 175,000 | $875 |
| My plan: $1,000 a month on groceries, restaurants and transit, $250 on the rest | 39,000 | 199,000 | $995 |
| All on groceries, dining and transit (6 per $1) | 45,000 | 205,000 | $1,025 |
So the floor is $875 and the ceiling is $1,025. My spending is mostly groceries, restaurants and transit, so I expect to land near the top. I still plan on about 180,000 points, or $900, because not every purchase lands in the category you expect. If it comes in higher, good.
What $900 buys: a weekend at the Château Frontenac
I don't want points for a trip I'd never take. I want hotels and rental cars, because that's how I travel. So I priced the weekend I'd actually book: two nights at the Fairmont Le Château Frontenac in Quebec City, on Expedia For TD, for Friday November 13 to Sunday November 15, 2026, two people.
The cheapest room was a Fairmont Queen at $1,075.12 for two nights, taxes and fees included.
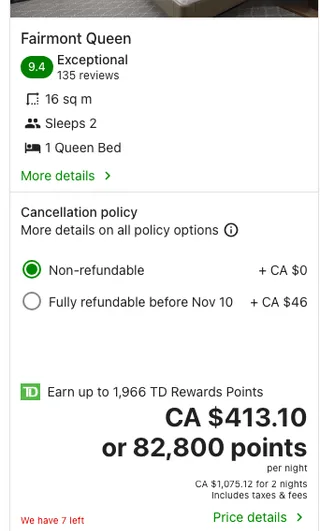
expediafortd.com, October 24, 2026, for November 13 to 15. Look at the small print under each price: the two-night total with taxes. That's the number your points have to cover.
So, plainly: $900 doesn't quite cover it. But a $1,075 hotel is over $500, so it should also trigger the $100 travel credit (next section). $900 of points plus $100 of credit is $1,000, and I'd pay about $75 in cash. If my spending lands at the $995 I expect, the points cover it outright. Prices swing a lot by season: the same room for January 15 to 17, 2027 was $1,289.32. Check your own dates.
Not a Fairmont person? The points work the same way on rental cars: 200 points = $1. Split them between a car for the drive and a cheaper hotel, and the $900 goes further.
Expedia For TD is easier than it sounds
I'm not a fan of bank travel portals. This one is fine, because if you travel once or twice a year, it is just Expedia.
- Sign in at ExpediaForTD.com with your normal TD online banking login.
- Search for flights, hotels, packages or car rentals, the same way you would on Expedia.
- On the billing page, choose how many points to use, in steps of 200. All of them, or part.
- Pay with the card. TD charges the full price, then credits back the points' dollar value in 3 to 5 business days.
There are no blackout dates and no seat limits on flights, because you are buying a normal ticket. Whatever you pay in cash on top still earns 8 points per dollar. One habit worth keeping: check the same flight on the airline's own site before you book. If Expedia's price is higher, the difference comes out of your $900.
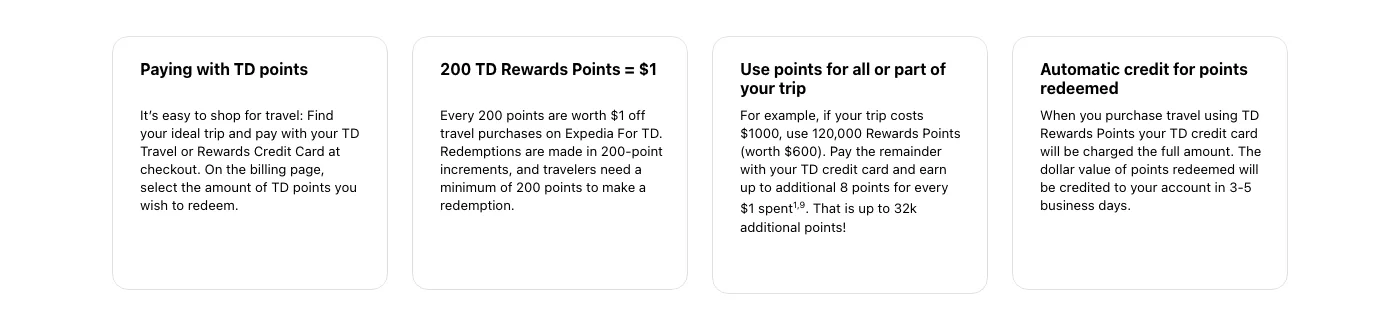
expediafortd.com, October 24, 2026. The second box is the whole rate card: 200 points = $1, whatever you book.
The $100 travel credit has a catch
TD gives one $100 TD Travel Credit per calendar year. The fine print (footnote 23) says it only triggers on a $500+ hotel, vacation rental, or package that includes one, booked on Expedia For TD. A flight on its own doesn't count.
Here is the churning angle: it is per calendar year, not per card year. Open the card in the fall, book a hotel before December 31, and book another one in the new year. That's two $100 credits before the second-year fee shows up. Only worth it if you were going to book those hotels anyway.
Four lounge visits: good for a layover
The card comes with 4 free lounge visits a year through the Visa Airport Companion Program, at 1,200+ lounges worldwide. You have to enrol first. TD values extra visits at US$35 each.
Let me be honest: these aren't the best lounges. You won't find the fancy airline ones on this list. But on a three-hour connection, a quiet seat, a drink and something to eat beat a bench at the gate. If you fly with a connection once or twice a year, four visits covers it.
What it takes to get the bonus
- Income: $60,000 personal or $100,000 household.
- First purchase: 20,000 points. Do it right away; you also have to activate and make a purchase within 3 months to get the fee rebate.
- The big one: 140,000 points for $7,500 in purchases within 180 days. That is about $1,250 a month for six months. Put your normal spending on it. Don't buy things to hit the number.
- Annual fee: $139, rebated for year one. A first extra card is $50, also rebated if you add it during the offer.
- Timing: points can take up to 8 weeks after you qualify.
- Not for repeat customers: you can't get the offer if you activated or closed this same card in the last 12 months.
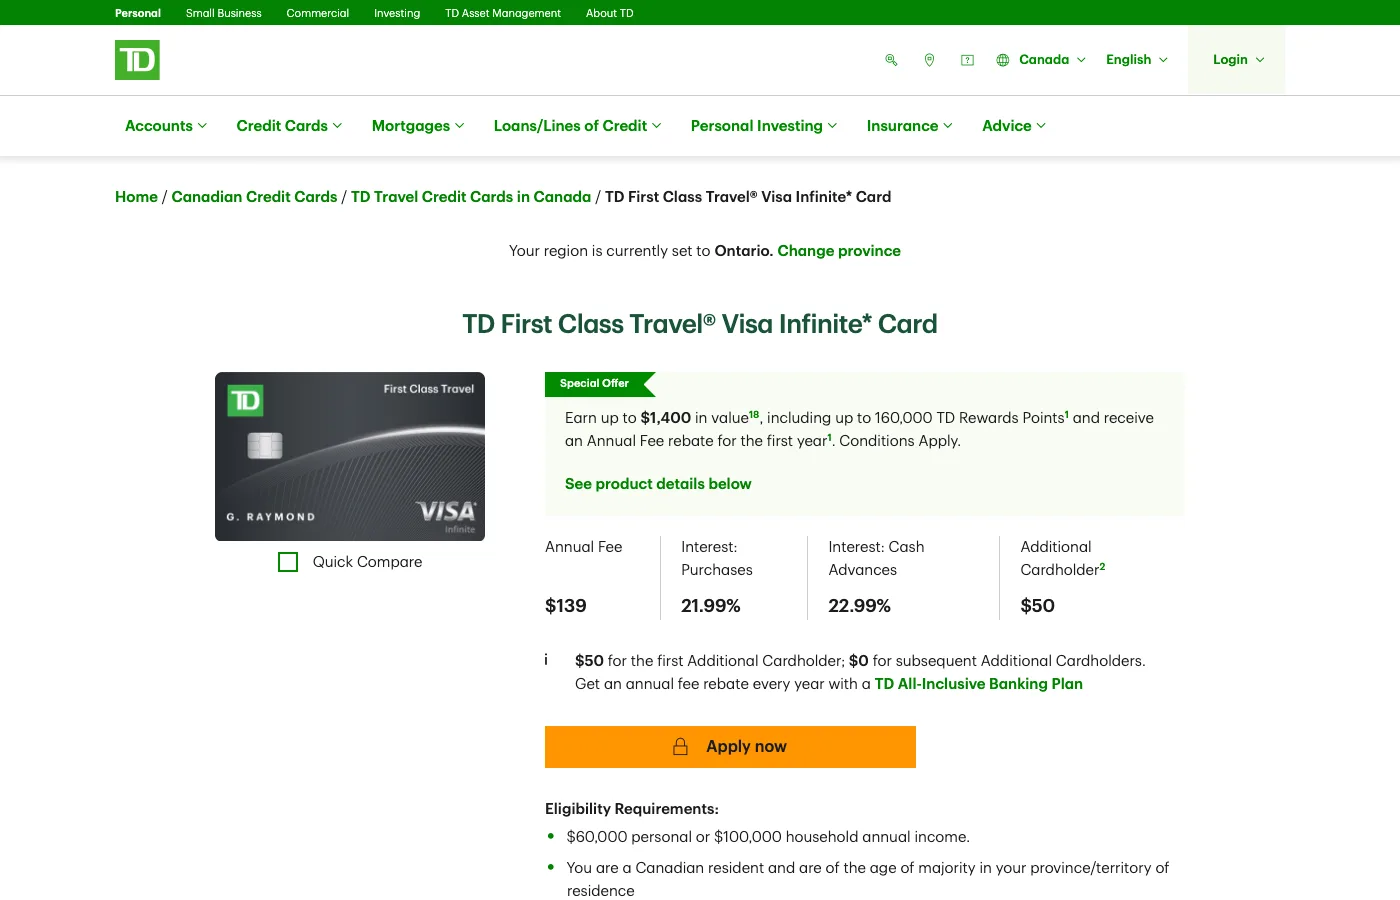
td.com, October 24, 2026. The honest part of the page: $139 a year, 21.99% interest and the $60,000 income line.
That 21.99% is the reason for my one rule: pay the card in full, every month. One month of interest on $1,250 is about $23. Carry a balance for a few months and you've handed back a chunk of the $900.
What it earns after the bonus
At Expedia For TD's rate (200 points = $1), here is what each category is worth in plain dollars:
- Travel on Expedia For TD: 8 points per $1, so $4 back per $100.
- Groceries, dining, public transit: 6 points per $1, so $3 per $100 (on the first $25,000 a year in each).
- Recurring bills and streaming: 4 points per $1, so $2 per $100.
- Everything else: 2 points per $1, so $1 per $100.
Redeem anywhere else and cut those in half. Link the card to Starbucks Rewards and you earn 50% more points there.
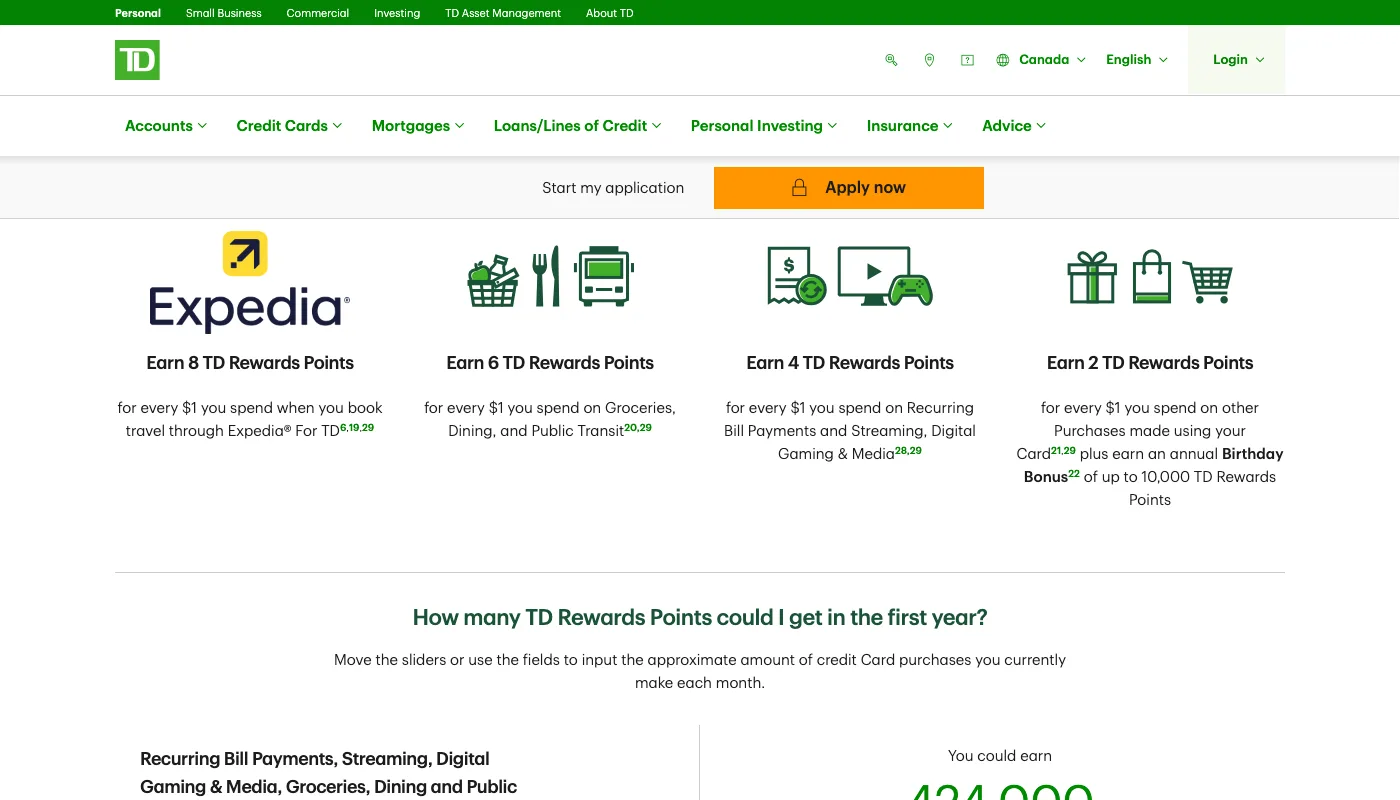
td.com, October 24, 2026. Under each number is a footnote. The 6 and the 4 stop at $25,000 a year.
My churning plan
- Apply, then buy something small the same week. That locks in the 20,000 points and the fee rebate.
- Months 1 to 6: normal spending, about $1,250 a month, paid in full.
- Around month 8: the 140,000 points land. Book the Quebec City weekend on Expedia For TD; it's a $500+ hotel, so it uses the travel credit too.
- Month 11, before the $139 fee posts: pick one of three.
- Downgrade to the no-fee TD Rewards Visa. TD Rewards points move over one-to-one, so nothing is lost, and the account stays open for my credit history. Only do this after the bonus has posted: TD warns that switching cards early can forfeit unawarded points.
- Cancel. Redeem first. TD's terms give you 90 days after closing, with fewer ways to redeem.
- Keep it if you hold TD's All-Inclusive Banking Plan, which rebates this card's fee every year. That plan costs $30.95 a month unless you keep $6,000 in it, so it only makes sense if you already do.
- Come back later. The 12-month rule means I can try again a year after I close or switch out of it, if the offer is still good.
If you're new to this, start with Credit Card Churning 101. It explains the credit-score side and why I space applications about 90 days apart.
Who should skip it
- You never use Expedia. Then the points are worth half, and about $450 for $7,500 of spending is ordinary.
- You want airline miles. TD points don't transfer to Aeroplan or anyone else. Look at the TD Aeroplan Visa Infinite instead.
- You spend in other currencies a lot. It charges 2.5% on foreign purchases. My abroad post has better cards for that.
- You carry a balance. At 21.99%, this card costs you more than it gives.
For everyone else, especially if you take one or two trips a year: this is an easy $900, with the paperwork of one application. That's why it's my Card of the Month, and why I'm applying.
Before you apply: confirm the live offer on the bank's own page. Everything in this post is dated October 24, 2026, the day it was written, and banks change their offers whenever they like. General information, not financial advice, and no affiliate links. Full details in our Terms of Use.